Although Capital One (currently trading at $197.72 per share) has gained 11% over the last six months, it has trailed the S&P 500’s 21.1% return during that period. This might have investors contemplating their next move.
Is there a buying opportunity in Capital One, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Capital One Not Exciting?
We’re passing on Capital One for now. Here are three reasons why there are better opportunities than COF, plus one stock we’d rather own.
1. EPS Trending Down
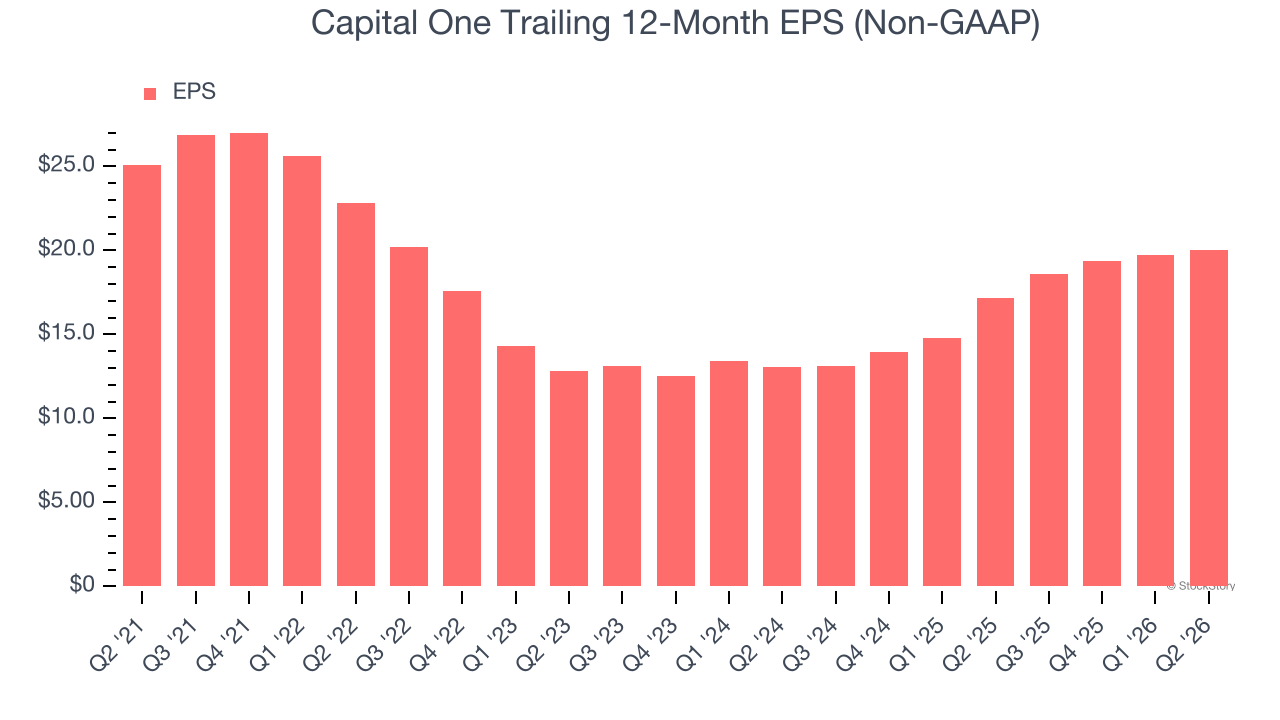
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Capital One, its EPS declined by 4.4% annually over the last five years while its revenue grew by 16.3%. This tells us the company became less profitable on a per-share basis as it expanded.
2. Declining TBVPS Reflects Erosion of Asset Value
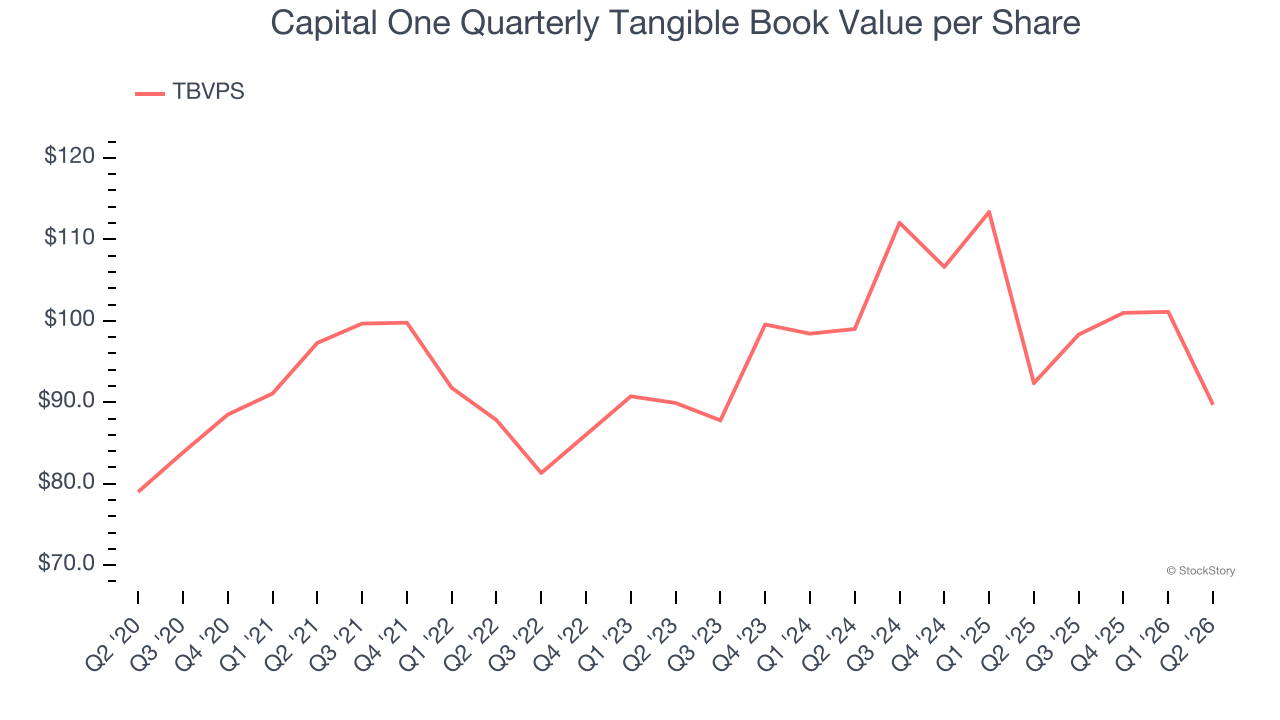
Tangible book value per share (TBVPS) is a crucial metric that measures the actual value of shareholders’ equity, stripping out goodwill and other intangible assets that may not be recoverable in a worst-case scenario.
Disappointingly for investors, Capital One’s TBVPS continued freefalling over the past two years as TBVPS declined at a -4.8% annual clip (from $99.00 to $89.71 per share).
3. Previous Growth Initiatives Haven’t Impressed
Return on equity, or ROE, quantifies financial firm profitability relative to shareholder equity — an essential capital source for these institutions. Over extended periods, superior ROE performance drives faster shareholder wealth compounding through reinvestment, share repurchases, and dividend growth.
Over the last five years, Capital One has averaged an ROE of 9.2%, uninspiring for a company operating in a sector where the average shakes out around 10%.
Final Judgment
Capital One’s business quality ultimately falls short of our standards. With its shares underperforming the market lately, the stock trades at 8.9× forward P/E (or $197.72 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re fairly confident there are better investments elsewhere. Let us point you toward the Amazon and PayPal of Latin America.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.